A service customer can have positive equity and no interest in changing vehicles. That simple fact is easy to lose when a dealership turns a database calculation into an outreach list.
The calculation is also thinner than it was. Experian's first-quarter 2026 report puts the average new-vehicle loan at 69.48 months and the average payment at $770, with 35.55 percent of new loans and 31.54 percent of used loans running past 72 months. A customer three years into an 84-month note is not sitting on equity, and the Consumer Financial Protection Bureau's 2024 review of its auto finance data pilot made the plain point that rolling negative equity into the next loan leaves the customer further underwater. The sales manager who owns the service-to-sales program should treat an equity list as a list of candidates, not a list of conversations.
Equity is useful. It can indicate that a customer has options. It may help identify a financially practical moment to discuss a purchase or trade. But it says nothing by itself about the customer's priorities, current experience, timing, or permission to begin that conversation. When every calculated opportunity receives the same message, the dealership mistakes eligibility for intent. The result can feel irrelevant at best and intrusive at worst.
| Signal | Type | What it tells the store | What it justifies on its own |
|---|---|---|---|
| Estimated positive equity above a threshold | Equity | The customer could trade without rolling negative equity | Nothing yet; a candidate for review |
| Lease maturity within 120 days | Equity and timing | A decision window exists whether or not the store opens it | A scheduled, optional conversation |
| Repair estimate above a share of the vehicle's value | Intent | The customer is already weighing repair against replacement | A same-visit comparison, offered once, by the advisor |
| Customer asked about a model, trade value or payment in the last 90 days | Intent | The customer raised it | A reply to the question the customer asked |
| Mileage pattern or household change the customer told the store about | Intent | Needs have changed, on the customer's own account | A relevant, specific offer |
| Open repair, dispute, recent decline or opt-out | Suppression | The relationship is not in a state for a sales conversation | Stop. Nothing is sent |
Separate the signals before you act on them
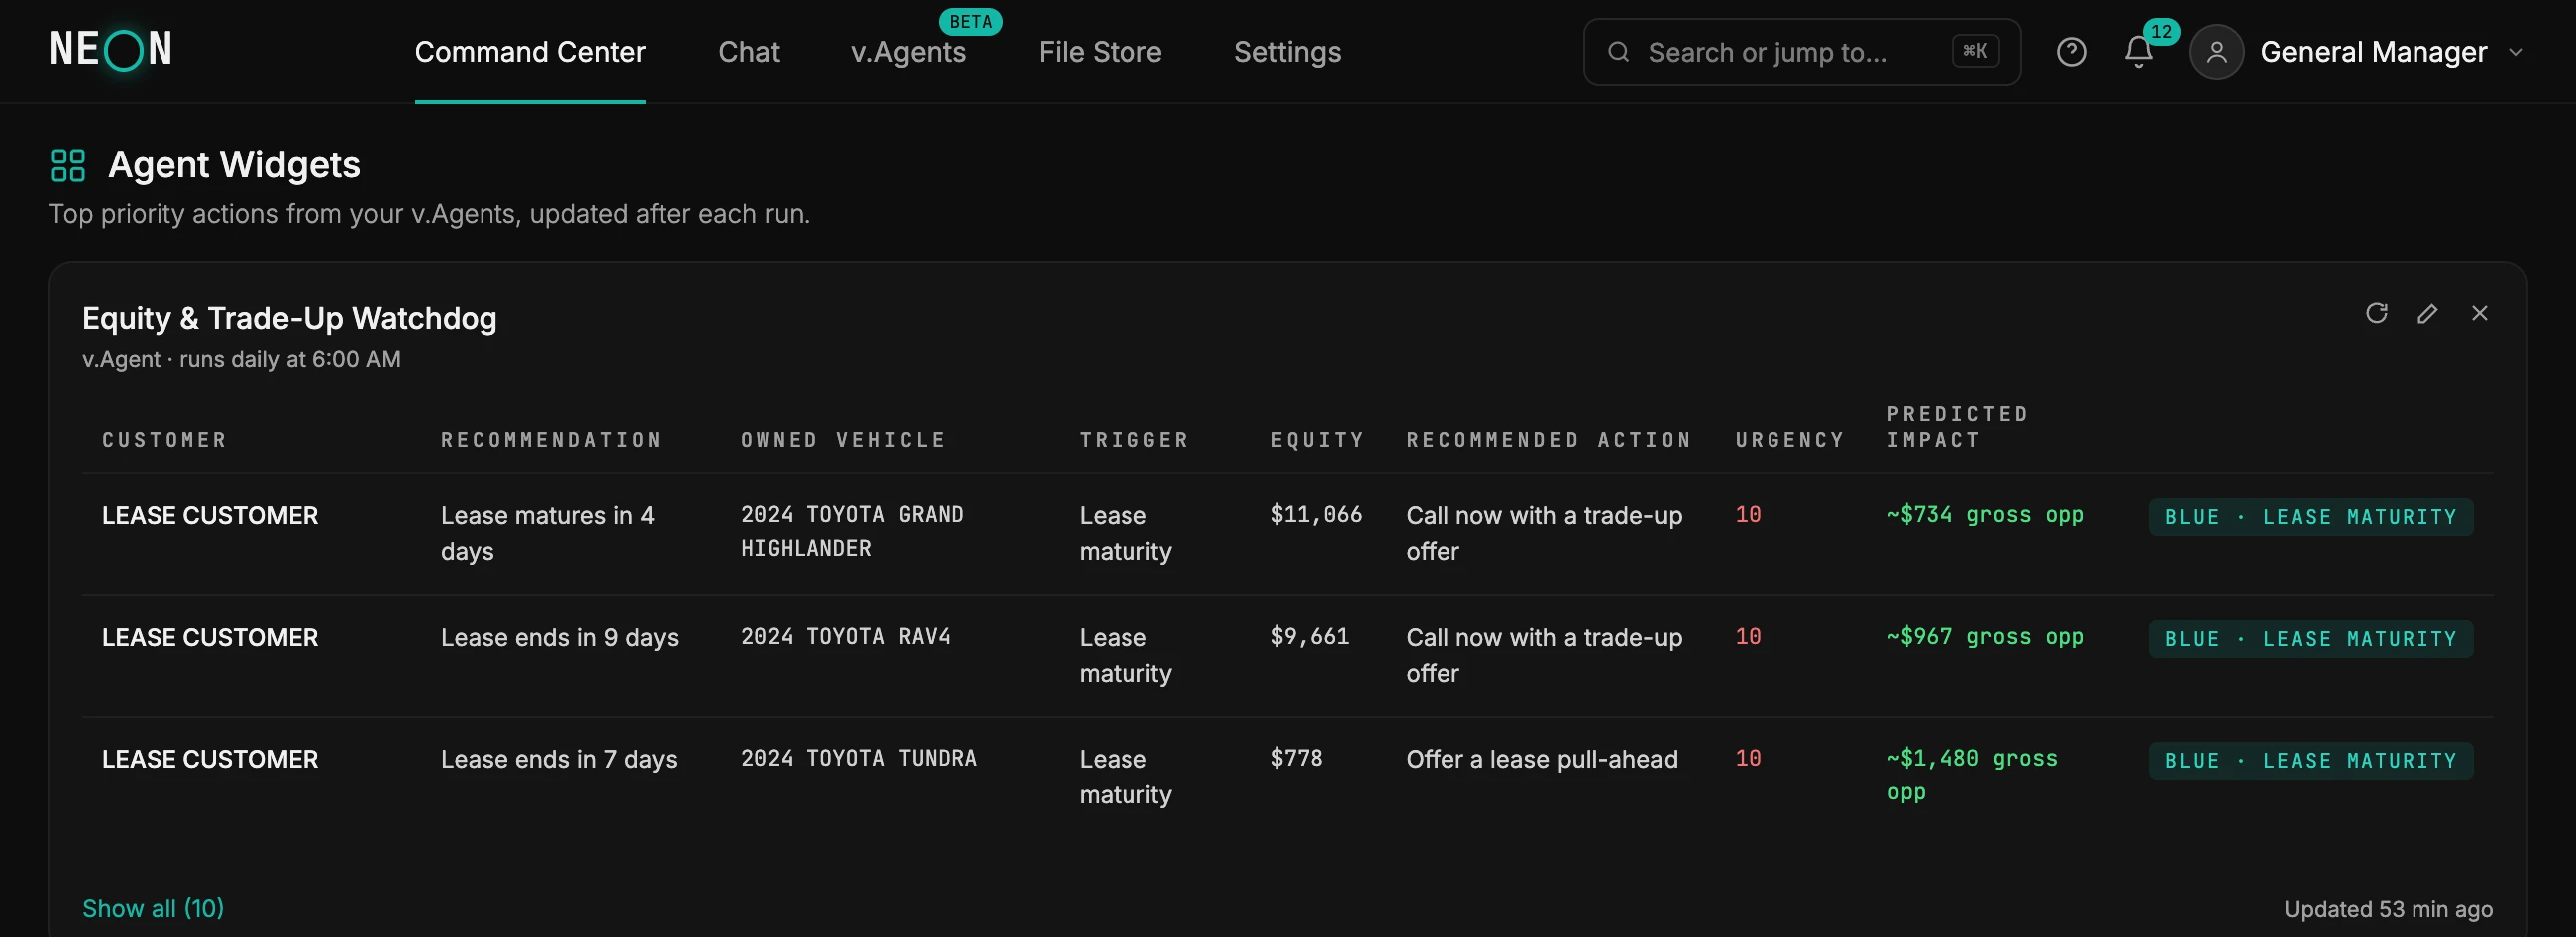
The figure above does the sorting. Equity signals, a positive position or a lease maturing, say the customer could. Intent signals, a repair estimate that rivals the vehicle's value, a question the customer asked about a model or a payment, a change in needs the customer mentioned, say the customer might want to. Suppression signals, an open repair, a dispute, a recent decline, an opt-out, say the relationship is not in a state for the conversation at all.
Only an intent signal justifies a conversation on its own, and even then the right form is a reply to what the customer raised, not a pitch. An equity signal with no intent beside it is a reason to watch, not to call.
Start with a reason the customer would recognize
The strongest service-to-sales conversations have a specific, customer-centered reason to occur. A repair estimate may prompt a customer to compare keeping and replacing the vehicle. A lease milestone may create a genuine decision window. A model the customer has previously asked about may now be available. A change in driving needs may be visible because the customer told the dealership, not because a system guessed.
That context sits across several places: service history, the customer relationship management (CRM) system, inventory, deal terms. Deal terms and equity estimates can clarify what is possible, but they should not be presented as certainty before a qualified person reviews them. The job is not to combine every available field into a more elaborate pitch. It is to determine whether there is a respectful reason to start a conversation.
Timing includes the customer's current experience
A mathematically attractive opportunity can still arrive at the wrong moment. A customer waiting on a delayed repair, disputing a charge, or asking for a service update should not be routed into a sales sequence because an equity threshold fired.
The dealership needs suppression rules that reflect the whole relationship, and they need to run before prioritization, not after. An unresolved complaint, a recent decline, a communication opt-out, or an active service issue should change what happens next. So should uncertainty about identity, ownership, or the accuracy of the underlying estimate. A customer who came for service should receive the service experience promised. If a purchase conversation becomes relevant, the transition should be clear and optional, and the advisor or manager should decide whether and who.
Permission makes relevance sustainable
Useful outreach gives the customer control. It explains why the dealership is reaching out, avoids manufactured urgency, and makes declining easy. It does not reveal an unsettling amount of internal detail or imply that the dealership knows more about the customer's finances than the customer chose to discuss.
The language matters. Telling a customer that today's repair estimate may make it useful to compare repair and replacement options is a transparent offer. Telling a customer the store knows they have equity and can lower their payment today carries assumptions that may be wrong. Permission also applies to the data behind the message: access to service notes and financial details limited to people with a legitimate role, and opt-outs honored across departments, not interpreted separately by sales and service.
Prioritization should support judgment
A service lane can produce more potential opportunities than a team can thoughtfully review. The answer is not to send more messages. It is to prioritize the situations with the clearest relevance and give a person the evidence needed to decide: why it surfaced, which facts support it, what could make it inappropriate, and what action is proposed. The reviewer approves, redirects, waits, or closes with a reason, and that decision stays visible so the same customer does not reappear in another queue the next day. A large list is not evidence of a healthy program. Equity can help open a door. Relevance, timing, permission and human judgment determine whether the dealership should walk through it.
Questions for the next opportunity review
- What customer-recognizable reason, beyond calculated equity, justifies each service-to-sales conversation?
- Which active service issues, declines, complaints or communication preferences should suppress or delay outreach, and do they run first?
- Can a manager review the supporting context and approve the next action before the customer is contacted?
Sources
- 01Experian, New Experian Automotive Report Shows Nearly One-Third of Automotive Loans Exceed Six Years, 2026-05-28. Accessed 2026-11-07.Q1 2026 State of the Automotive Finance Market; average new loan term 69.48 months, used 67.73; average new payment $770, used $531; 35.55% of new and 31.54% of used loans over 72 months.
- 02Consumer Financial Protection Bureau, Data Spotlight: Negative Equity Findings from the Auto Finance Data Pilot, 2024-06-17. Accessed 2026-11-07.Including negative equity in financing can place consumers further underwater on their next loan.
William founded Vehicle AI to put an accountable operating layer between dealership data and daily management. Before that he worked at Bain and Capital One Auto Finance and spent several years at start-ups. He writes The Vision and The Box.
LinkedIn